Up to $2M of life insurance that covers the way you climb.
No climbing exclusion, no medical exam, and no premium surcharge for your sport. I'm a climber and a licensed advisor, and I built this plan for our community.
Tell a regular insurer you climb, and your price goes up or your coverage shrinks.
Fully underwritten policies usually handle climbers one of two ways. Either they exclude climbing deaths, which defeats the purpose, or they add a surcharge that's often around $4 per $1,000 of coverage. On $1M, that's roughly $4,000 more a year.
Full underwriting
- ✕A climbing exclusion or a surcharge of about $4 per $1,000
- ✕A medical exam, bloodwork and weeks of back-and-forth
- ✕An activity questionnaire for every sport
- ✕Often declined for alpine climbing or paragliding
A stack of 4 simplified-issue plans
- ✓No climbing exclusion and no sport surcharge
- ✓No medical exam. Short health questions answered online
- ✓Up to $2M total ($500k per insurer)
- ✓Your price is locked for the whole term
Four Canadian insurers, each up to $500k, in one simple application process.
Simplified-issue policies skip the medical exam and don't penalize mountain sports, but each insurer caps coverage at $500k. So I combine them. You get the coverage your family needs, usually for less than one rated or excluded policy.
Philip explains climber coverage.
Why regular policies exclude or surcharge climbers, how the 4-insurer stack works, and what to disclose on your application.
Watch the video
See what you qualify for.
Two quick questions, then build your own plan. No email needed.
What do you do in the mountains?
Pick at least one activity to continue.
A little about you
Covered by the people who get it.
Far better than the competitors. We spend over a month applying for different life insurance providers and getting a late answer showing exceptions for climbing and skiing. Philip was quickly able to help navigate the process and set us up with life insurance that actually covers our lifestyle. He made it easy, and was very open and friendly. We never felt pressured, and think we got exactly the coverage needed.
I had life insurance previously both though my employer and though another provider. I'm an avid ice climber, backcountry skier and downhill mountain biker. I thought I was covered for these sports. With my existing insurance. Philip with Affinity Life advised me to contact my existing providers to find out if I was covered for AD&D and accident. Turns out I wasn't at all. I have a family and if something were to happen they would have received no benefit. Affinity has the most affordable extreme sports coverage I've come across. Philip is amazing. Super knowledge and their website is really slick. Very easy to understand the coverage and costs with no hassle and no pressure. Hands down I would and do recommend Affinity to all my peers. This is must have coverage for those of us engaged in these types of sports. Thank you Affinity!!
If you live for the outdoors, Phil is the person to call. He truly understands the realities of climbing, and backcountry trips, and how that impacts coverage. The process was smooth, transparent, and zero pressure. I feel confident knowing I’m properly protected while doing what I love.
Philip at Affinity Life is the real deal. Getting life insurance for high-risk adventure sports can get complicated fast, but he handled everything with expertise and zero fuss — found me solid coverage, explained my options clearly, and made the whole experience genuinely easy. Highly recommend, especially if you lead an active or adventurous lifestyle.
Affinity Life made it possible for me to qualify for affordable term life insurance when other insurance quotes excluded coverage for participation in backcountry skiing and other "extreme sports". Affinity Life's web platform is easy to use and Phillip is professional and knowledgeable. I highly recommend Affinity Life, especially if you're a regular participant in mountain sports.
Philip was a pleasure to work with. Had spent a long time going back and forth with multiple other providers. Always struggling to find appropriate coverage that would cover climbing, skiing and paragliding etc. Philip understood what I required and was able to get me appropriate insurance coverage in less than a week.
So happy I found an insurance company that I can finally trust!! (Especially being a skier and climber, its awesome to know the founder is also a climber!) Was great how simple everything was online. Not having to go through the annoying sales calls to get the insurance I needed was a huge bonus!
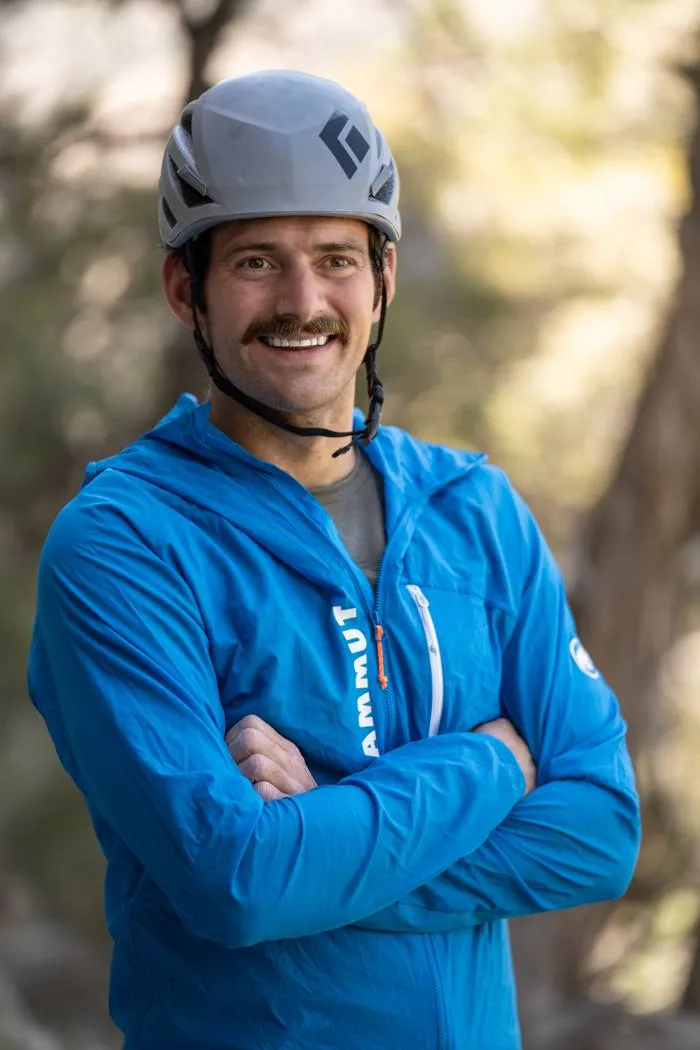
"It will never bring back our loved ones, but it can let our families grieve with one less overwhelming stress."
In 2020 I lost a close friend and climbing partner in an accident, and I saw firsthand what his family went through. I'd spent years in insurance and knew most policies quietly exclude the things we love doing. So I built Affinity Life to get climbers properly covered, simply.
I read every contract I recommend. It's the same coverage that protects my own family.
Know your options before you apply.
How insurers really treat climbers, and how to avoid an exclusion.
2 min readWhat underwriters ask about avalanche terrain, and how to answer.
2 min readCoverage for injuries you survive, not just the ones you don't.
3 min readThe Climber's Guide to Life Insurance.
The guide Philip wishes every partner had read before their next trip.
- The exact questions insurers ask climbers, and how to answer
- Exclusion vs rating vs simplified issue, compared
- A checklist to get your affairs in order before a big objective
What people ask before they apply.
Will a climbing accident actually be paid out?
The plans we place for climbers don't exclude climbing. As with any policy, answer the application honestly: a claim can generally only be contested for misrepresentation in the first 2 years.
Why four policies instead of one?
Simplified-issue plans skip the medical exam and don't surcharge mountain sports, but each insurer caps coverage at about $500k. Combining them gets you to $2M, usually for less than one fully underwritten policy with a sport rating.
Is it more paperwork?
Not for you. You answer one set of questions, and we handle the applications with each insurer.
What if I do something more extreme?
Expeditions above 6,000 m, free soloing, BASE and similar activities need a personal review. Book a call and I'll tell you honestly what's possible.
Do I need less than $500k?
Then one plan does it, usually with UV, which tends to have the lowest price.
Get covered before your next trip.
Take the 60-second check, or book 15 minutes with Philip and he'll lay out your options.