How stacking simplified-issue life insurance works
- Each simplified-issue insurer caps coverage, usually at $500,000.
- Combining up to 4 insurers can reach $2,000,000 with no climbing exclusion and no medical exam.
- Limits shrink with age, and not every insurer offers every term length.
Why one policy isn't enough
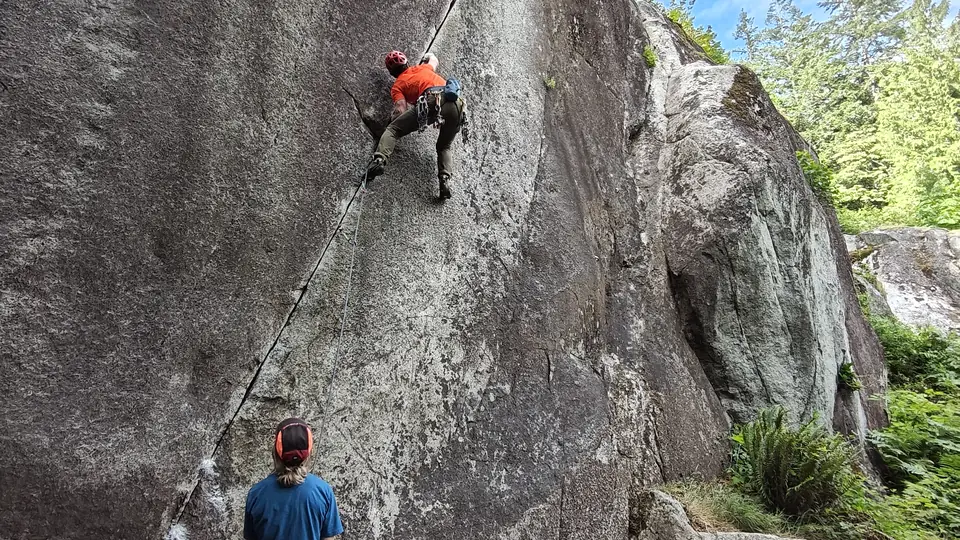
Simplified-issue life insurance skips the medical exam. You answer a short set of health questions, and the insurer decides quickly. For climbers, the big advantage is that the plans we use don't exclude or surcharge mountain sports.
The catch is that each insurer limits how much it will issue this way, usually $500,000. That's often not enough for a family with a mortgage and kids.
How the stack works
Instead of one large policy, we place several smaller ones with different Canadian insurers:
| Insurer | Up to | Notes |
|---|---|---|
| UV Insurance | $499,999 | Usually the lowest price, so it goes first |
| iA Access Life | $500,000 | 15, 20 and 25-year terms |
| CPP | $500,000 | 10, 20 and 25-year terms |
| Humania | $500,000 | 10 and 20-year terms |
The estimator fills the cheapest plan first, then the next cheapest, until it reaches the coverage you chose.
Age and term limits
Limits change with age. UV, for example, issues up to $499,999 to age 45, $350,000 from 46 to 55 and $250,000 from 56 to 65. CPP drops to $350,000 after age 60. Longer terms also stop at younger ages. Pick a 30-year term and fewer insurers can take part.
The climber estimator applies all of these rules automatically and shows you when an insurer drops out.
An example
A 41-year-old non-smoking man who wants $1,000,000 for 20 years:
- Climber stack: about $153 a month (two simplified-issue plans, no climbing exclusion)
- Rated full-underwriting policy: about $431 a month (standard price plus a typical $4 per $1,000 climbing rating)
These are estimates. Final prices are confirmed when you apply.
Is it more paperwork?
Not really. You answer one set of questions, and we handle the applications with each insurer. Most people are approved within about a week.
FAQ
Is it legal to have several policies at once?
Yes. You disclose your other coverage on each application, and each insurer checks that the total is reasonable for your income and needs.
Do I pay several premiums?
Yes, one per insurer, each drawn monthly. The estimator shows the monthly total so you can compare it with a single policy.
What if I only need $500,000?
Then one plan usually does it, often with the insurer that has the lowest price at your age.
Philip Setter has been a licensed life insurance advisor since 2014 and founded Affinity Life in 2020. He's a climber, ice climber and ski tourer based in Calgary.