Life insurance for ice climbers and mountaineers
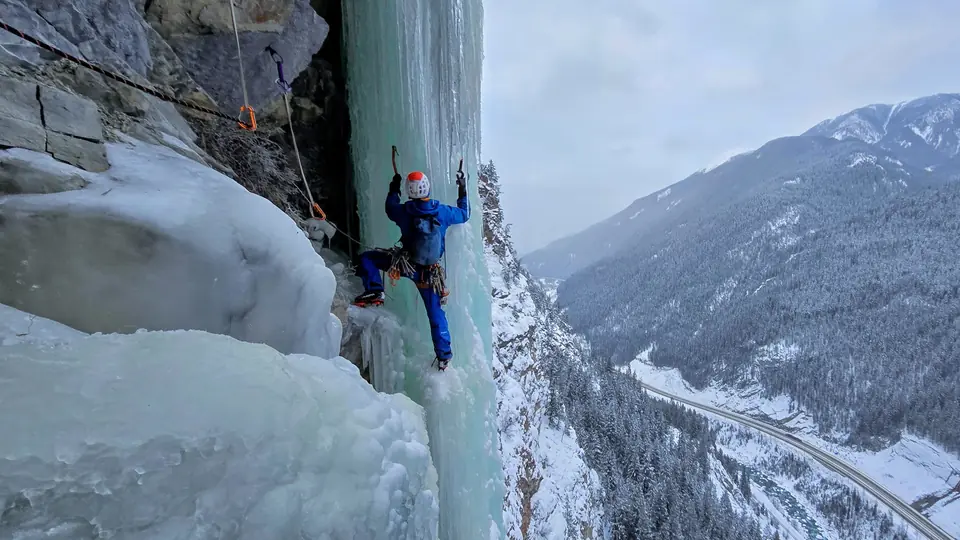
- Altitude is the biggest factor. Most questionnaires ask about peaks above 4,000 to 6,000 metres.
- Ice climbing and alpine routes are treated like other hazardous climbing.
- Expeditions above about 6,000 m need a personal review.
How underwriters see alpinism
Waterfall ice, mixed climbing and alpine routes all sit in the same bucket as outdoor rock on most applications. What changes the answer most is altitude and where in the world you climb.
What they ask
- The highest altitude you've climbed to, and plan to
- Expeditions abroad, and whether they're guided
- Solo climbing, and routes by grade
- How often you climb ice and alpine routes
Outcomes on a regular policy
Local ice and alpine climbing often leads to a flat extra charge or a climbing exclusion. High-altitude expeditions are frequently postponed until you're back, or declined.
Getting covered
The simplified-issue plans in the climber plan don't exclude ice climbing or mountaineering, and there's no medical exam. For expeditions above about 6,000 m, free soloing or similar, book a call and Philip will tell you honestly what's possible.
FAQ
I'm planning an expedition. Should I buy before or after?
Before. Coverage bought after you've booked a big objective can be harder to get, and some insurers ask about planned trips.
Does guided climbing help?
It's one of the questions on most questionnaires, and it can help on a regular policy.
Philip Setter has been a licensed life insurance advisor since 2014 and founded Affinity Life in 2020. He's a climber, ice climber and ski tourer based in Calgary.