Paragliding and life insurance - what to expect
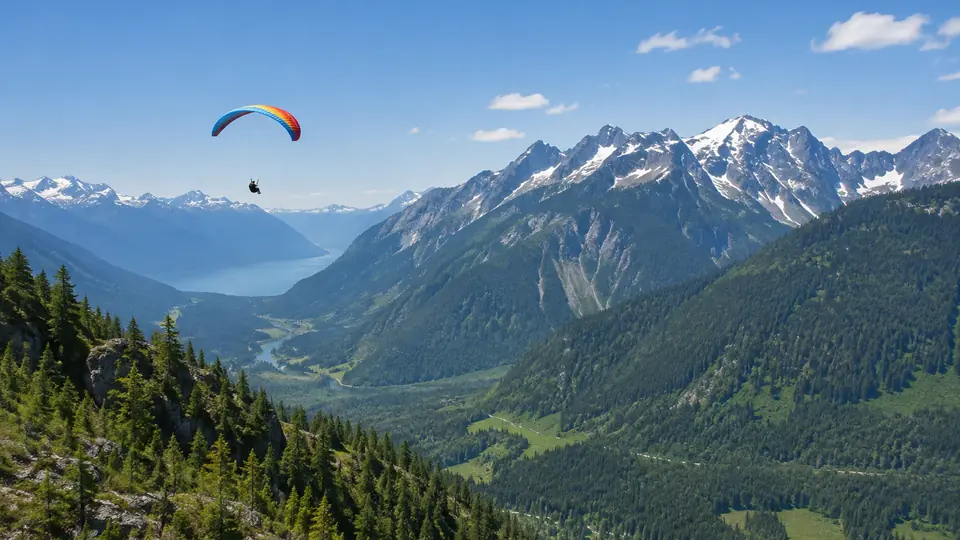
- Paragliding and hang gliding fall under aviation questions on most applications.
- Regular policies often add a flat extra, exclude aviation deaths or decline.
- Simplified-issue plans can be a way to get covered without an aviation exclusion.
Why pilots get extra questions
Most applications ask whether you fly "other than as a fare-paying passenger". Paragliding, speed flying and hang gliding all count. A yes leads to an aviation questionnaire.
What the questionnaire asks
- Your pilot rating and years flying
- Hours or flights per year
- Cross-country, competition, acro or speed flying
- Where you fly, including trips abroad
Common outcomes
On a fully underwritten policy, experienced recreational pilots are often offered a flat extra charge per $1,000 of coverage. Others get an aviation exclusion, which means no payout for a flying death. Newer pilots and competition pilots are more likely to be declined.
The simplified-issue route
The simplified-issue plans we use ask short health questions and don't carry a flying exclusion. Each caps coverage at around $500,000, so we combine several. Tell Philip exactly how you fly and he'll confirm what's possible before you apply.
FAQ
Does tandem flying as a passenger count?
Occasional tandem flights as a passenger are usually treated differently from flying as a pilot. Answer what the application asks.
Do competitions or cross-country flying matter?
Yes. Underwriters ask about both, and they can change the outcome on a regular policy.
Philip Setter has been a licensed life insurance advisor since 2014 and founded Affinity Life in 2020. He's a climber, ice climber and ski tourer based in Calgary.